Supported living

1. What is supported living?

Supported living is a housing model where a property is leased to a care provider or housing association, which then provides accommodation to individuals who need support to live independently. Unlike a standard buy-to-let, the landlord generally leases the property to an organisation rather than directly to the individual tenant, so there is no Assured Periodic Tenancy (APT) agreement in place.

2. Is supported living the same as social housing?

No. Supported living, social housing, HMOs and exempt accommodation can overlap, but they are not interchangeable terms. Supported living specifically involves accommodation where care and/or support is provided as part of the arrangement.

3. What type of property is suitable for supported living?

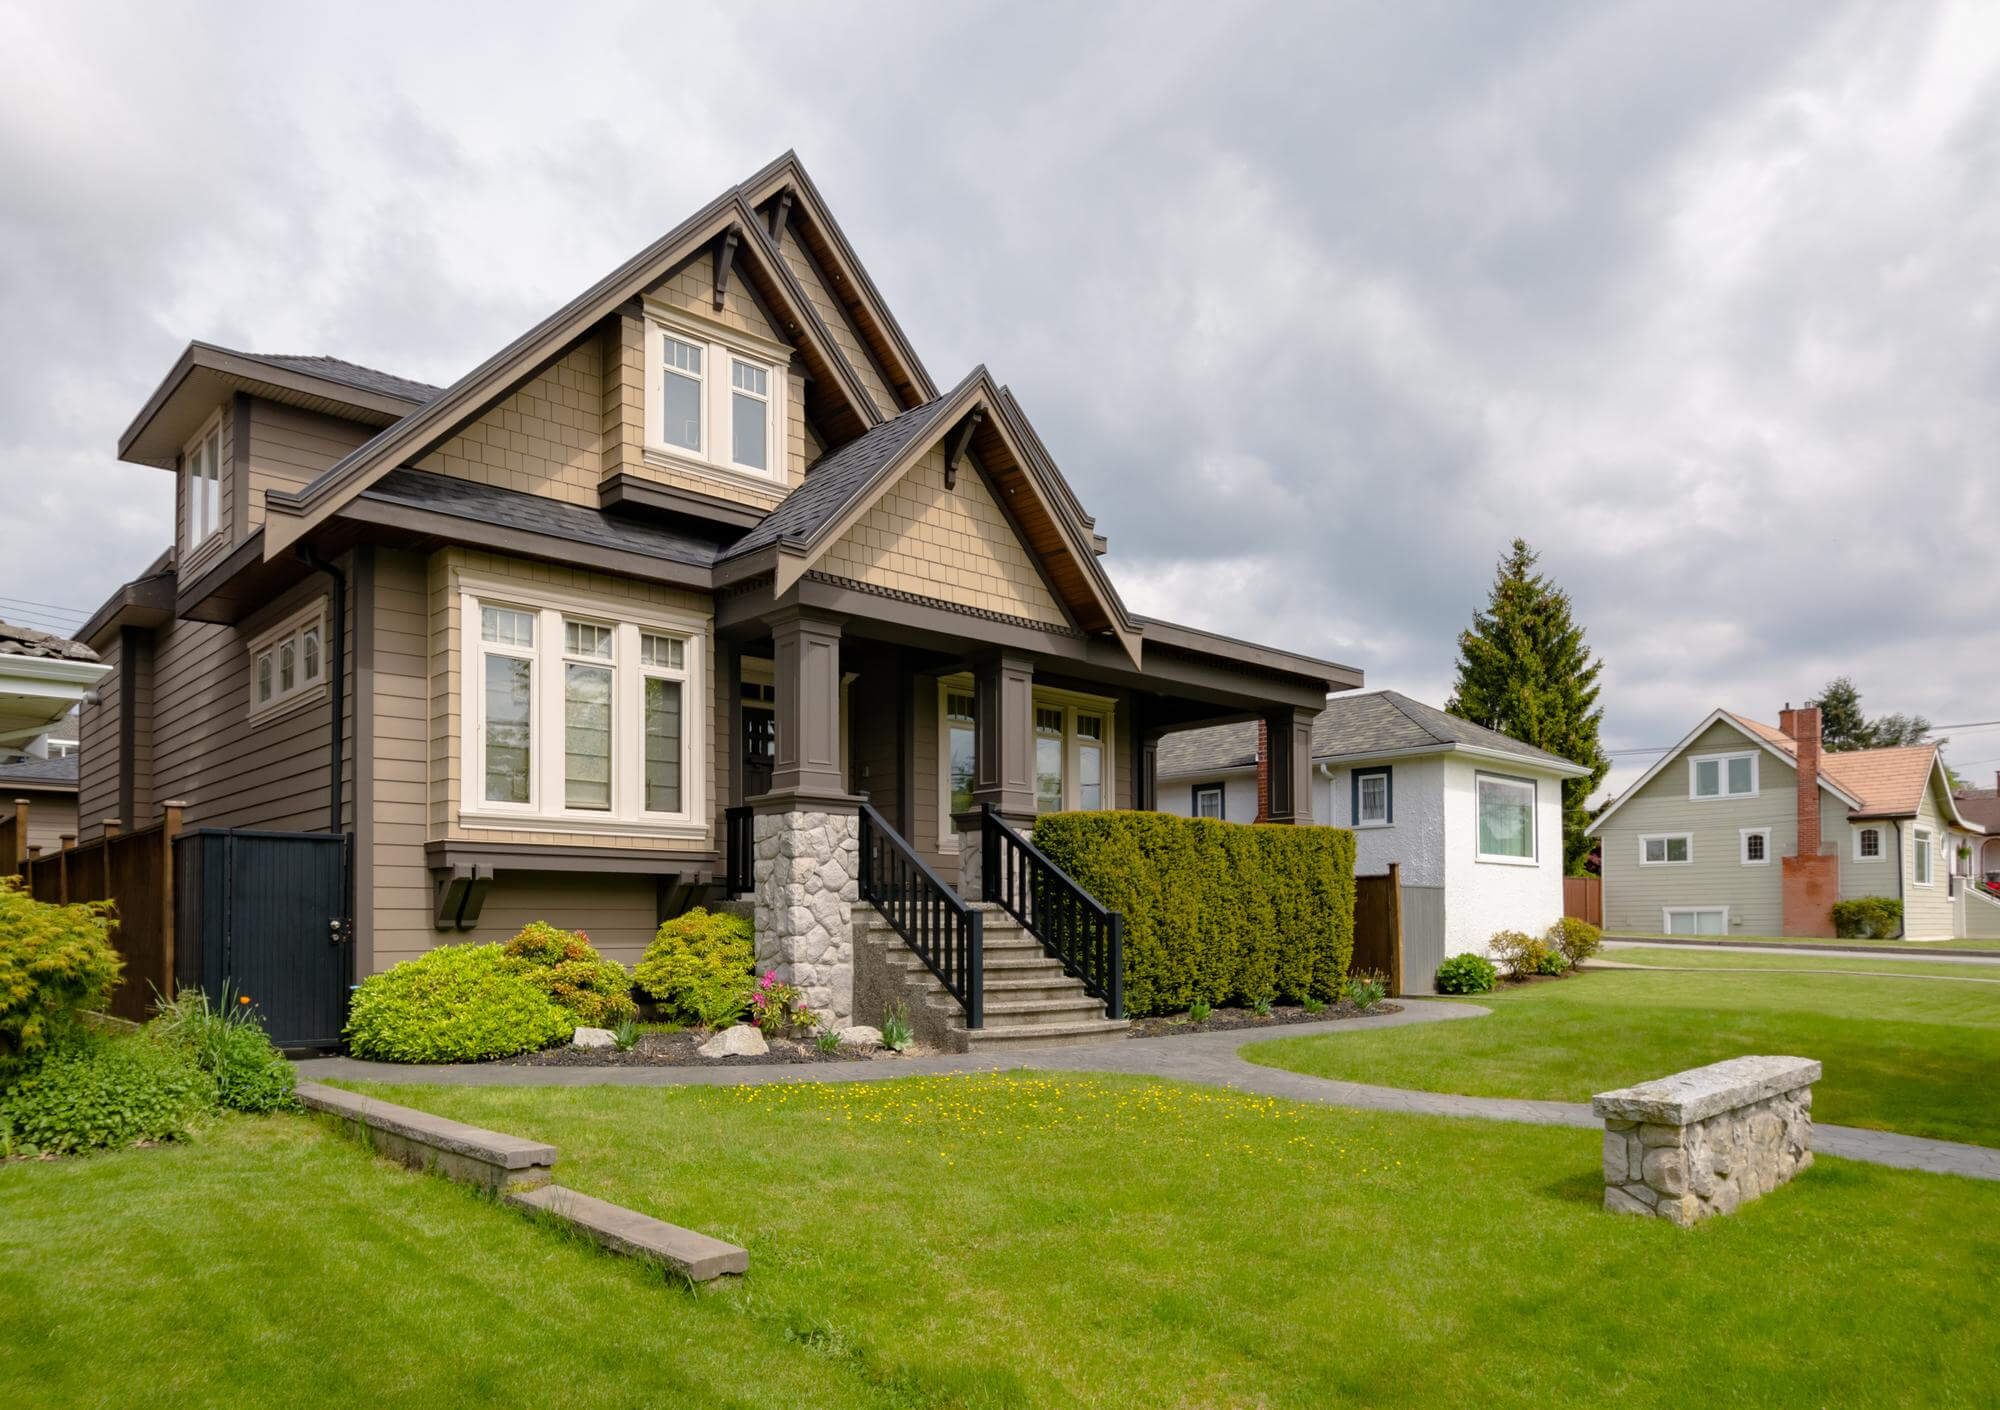
There is no single property type. Depending on the tenant group and provider requirements, suitable properties can include bungalows, self-contained flats, 3–6 bedroom houses, larger HMOs and, in some cases, blocks of flats. The important consideration is matching the property to the needs of the provider and intended occupants.
4. What is an FRI lease in supported living?

FRI stands for Full Repairing and Insuring. Under this type of lease, the provider takes responsibility for maintenance, repairs and insurance, subject to the exact terms of the lease. This can make the arrangement more hands-off for the landlord.

5. How long are supported living leases?

Leases tend to be for a number of years with break clauses. Most are 5 years long but some can go up to a 25-year term. Leases longer than 7 years will need to be registered on the Land Registry with an additional cost in legals to all parties involved. It is important that you have break clauses included whether a short term lease or longer.

6. Can a first-time landlord invest in supported living?

Potentially, yes, but finance can be more difficult for first-time landlords. Most specialist lenders look for property experience, with 12 months or more being a common threshold.

7. Do I need a special mortgage on a supported living property?

Yes, you need a lender that will allow supported living as a type of tenancy. Buy to let mortgages only allow the property to be let under an Assured Periodic Tenancy (APT) agreement which supported living does not fall under. Furthermore more, vulnerable tenants might be living in your property which require a specialist mortgage provider. Supported living is generally more complex from a lender’s perspective than straightforward BTL.

8. Does the supported living provider matter to the mortgage lender?

Yes, you need a lender that will allow supported living as a type of tenancy. Buy to let mortgages only allow the property to be let under an Assured Periodic Tenancy (APT) agreement which supported living does not fall under. Furthermore more, vulnerable tenants might be living in your property which require a specialist mortgage provider. Supported living is generally more complex from a lender’s perspective than straightforward BTL.

9. What should I check before signing a supported living lease?

Pay close attention to who is responsible for repairs, insurance, maintenance and major works. You should also understand the lease term, break clauses, renewal arrangements and dilapidations requirements. These details can have a significant impact on both your investment and your financing.

10. Which do I find first – the property, the tenant or the mortgage?

Pay close attention to who is responsible for repairs, insurance, maintenance and major works. You should also understand the lease term, break clauses, renewal arrangements and dilapidations requirements. These details can have a significant impact on both your investment and your financing.

10. Should I speak to a specialist broker before buying a supported living property?

Yes. Given the additional considerations around provider, lease structure, property use and landlord experience, it can be valuable to establish what finance is likely to be available before committing to a purchase or lease. Your posts specifically recommend speaking to a specialist broker before buying or committing to a lease

Our Services

Why River Finance?

At River Finance, we’re committed to delivering exceptional service and tailored financial solutions that set us apart. Here’s why landlords and property investors trust us:

Proactive & Passionate Professionals

Unbiased, Whole-of-Market Solutions

Tailored to Your Needs

Decades of Financial Expertise

Let’s Secure Your Financial Future

From mortgages to protection plans, we’re here to help you safeguard your investments and achieve peace of mind.

Schedule a Consultation

Ready to take the next step? Book a free, no-obligation consultation with one of our experts. We’ll discuss your needs and provide tailored solutions to help you achieve your financial goals.

Get in Touch

Scroll to Top